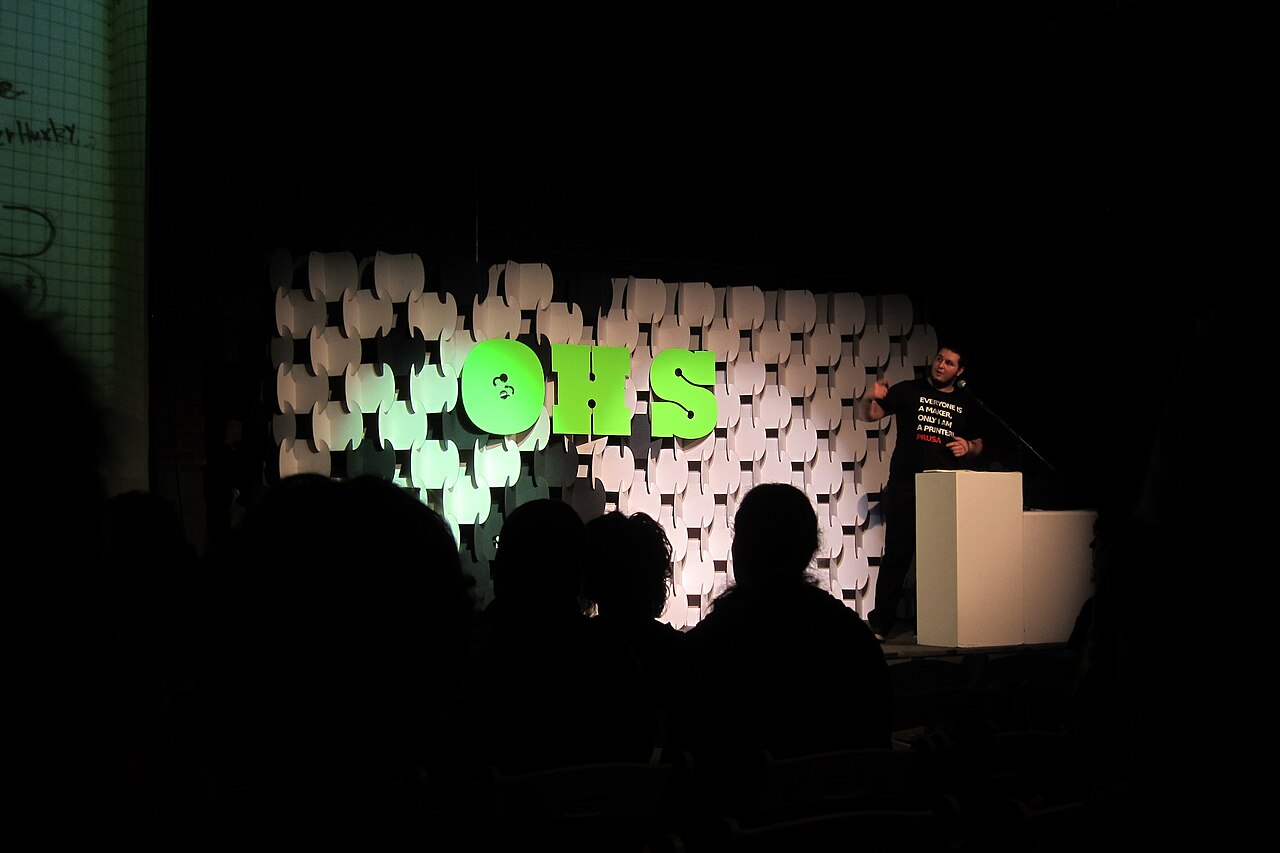
Josef Prusa has never been shy about the competitive pressure on his company, but his latest remarks are his starkest yet. In an interview published by 3D Printing Industry, the Prusa Research founder described the position of Western desktop printer makers as "one minute to midnight," argued that cheap desktop machines are pushing up into territory once held by industrial systems, and said state support for Chinese competitors is squeezing Western margins. He also suggested that cybersecurity teams, not just purchasing departments, should have a say in which printers organizations buy.
These are the arguments of an executive whose company competes directly with the firms he is talking about, and they deserve to be read that way. Some of what Prusa says can be checked against public records and market data. Some of it cannot. What follows separates the two.
The Argument: The Bottom of Industrial Is Being Eaten
Prusa's central claim is about market structure. Printers in the desktop bracket, he told 3DPI, "are consuming the lower tiers of the industrial" market. Machines that cost a fraction of a traditional industrial system are now good enough for a share of the work those systems used to handle. He was blunt about how established players are responding: "Many big and old players are in complete denial."
For a Western desktop maker, he argues, the problem is margin. Competition does not sink companies right away, he said, but "slims their margins, so it is like slow suffocation."
What the market data shows
Independent shipment data gives a more mixed picture than the word "midnight" suggests. Analyst firm CONTEXT's July 9 release on first-quarter 2026 shipments reported that total system revenues rose 32 percent year over year. Shipments of industrial systems, which CONTEXT defines as machines priced above $100,000, rose 18 percent, with China up 29 percent, North America up 9 percent, and Western Europe up 11 percent. Nine of the top ten vendors shipped more units than a year earlier.
That is not a picture of an industrial segment in collapse. It does show China's industrial market growing roughly three times faster than North America's. The growth is even sharper at the bottom: entry-level machines, priced under $2,500, saw shipments up 39 percent and accounted for 54 percent of all system revenues. Meanwhile professional systems ($2,500 to $20,000) saw shipments fall 22 percent, which CONTEXT attributes mostly to entry-level machines cannibalizing material-extrusion demand. That fits Prusa's narrower point, though price classes measure equipment cost, not the sophistication of the work.
Subsidies: The Part That Can Be Checked
Prusa's sharpest claim is that Chinese rivals benefit from state support Western firms do not get. He supplied Creality's draft Hong Kong listing document as evidence. That filing also describes a deduction equal to 200 percent of qualifying research and development spending when calculating taxable profits.
The grant figures are on the record. According to 3DPI, the filing reports government grants of RMB 34.6 million in 2023, RMB 10.1 million in 2024, and RMB 16.3 million in 2025. Those are real sums, but they are well below the 2023 level in both later years, and 3DPI notes that the disclosures show public support exists without establishing how much it reduced printer prices relative to product design, purchasing scale and manufacturing efficiency. Prusa's view that state support explains much of the pressure is his own interpretation. It is plausible, but the numbers alone do not prove it.
The Economics of a Plastic Case
One of the most useful parts of the interview is a rare look at production costs. Prusa said that for his own company, injection moulding becomes worth considering "when we know that we will make more than 60,000 pieces of that certain part." He supplied an example: for the MK4S LCD display case, mould tooling costs approximately 6,000 euros and the moulded part 0.18 euros, against 0.25 euros for printing the part or 0.32 euros including post-processing.
Those figures imply tooling pays for itself after roughly 43,000 to 86,000 parts, depending on which printing cost is used, so 3DPI reads the example as showing that printing stays competitive into tens of thousands of units rather than as a fixed 60,000-part threshold. By inference, a company shipping far more units per model than Prusa reaches that breakeven sooner on every part, which is one way volume favors the largest manufacturers.
Patents and Security
Prusa identifies two Anycubic filings concerning a filament-conveying device, US20250144881A1 and DE202024100001U1, and alleged in a July 2025 article that the design copied the multiplexer used in his MMU1. 3DPI reports that his response did not include a comparison between specific claims and dated prior-art documents, and that Anycubic had not replied to its invitation to respond. A patent filing is not a granted patent, and whether either filing overlaps with prior art is a question for patent examiners or courts, not interviews. 3DPI also points to a Texas federal jury's award of approximately $27.6 million to Stratasys against Bambu Lab, which Bambu says it will appeal, as a sign of how consequential patent rights have become.
On security, Prusa recommends that "every company's cybersecurity department review the risks of 3D printing and adjust their procurement rules accordingly," and that states do the same for defense, publicly funded universities and critical infrastructure. 3DPI reports that Section 849 of the US fiscal year 2026 defense authorization restricts new Department of Defense procurement contracts for covered additive-manufacturing machines beginning December 18, 2026, depending on company and jurisdictional criteria. It is not a general consumer sales ban. The recommendation to review purchases comes from a vendor that would benefit if buyers took it; the procurement restriction is a legal matter rather than his opinion.
What It Means for Makers
For people who buy and run desktop printers, the interview offers few immediate changes but several things worth watching.
- Margin pressure is the thing to watch. If Prusa is right, Western desktop brands may have less money to fund development, which could matter for long-term support and the next generation of machines. That is an inference, not a forecast from either source.
- Procurement rules are changing. If you print for a university, a defense contractor, or any organization with government work, check before December 18 whether the Section 849 restriction or a similar internal policy affects which machines you can buy.
- Know your printer's network setup. Whatever brand you run, decide on purpose whether it reaches a vendor cloud. LAN-only operation and isolated network segments are cheap ways to limit exposure.
- Patent fights may reach features you use. Multi-material systems are one contested area. Disputes there could affect which add-ons are sold in which markets, though that outcome is speculative.
Bottom Line
Prusa makes a coherent case: desktop machines are moving up into work once done on pricier systems, Chinese competitors receive documented state support, and Western makers face margin pressure. The grant figures in Creality's filing are on the record, and CONTEXT's data supports the shift toward entry-level machines. The claim that subsidies decide the outcome and the patent-copying allegation remain his arguments, made by a competitor, and are not independently proven. CONTEXT's numbers show an industry that is growing overall. The open question is how much of that growth Western desktop makers will keep.