Amaero Inc., a Tennessee-based producer of titanium and refractory-alloy spherical metal powders used in additive manufacturing, has postponed its planned U.S. initial public offering, the company announced on September 24, 2026. The listing, which would have put shares on the Nasdaq Global Select Market under the ticker AMRO, was scrapped just days after Amaero filed the paperwork that would have set it in motion.
In its release, Amaero pointed to "adverse market conditions" as the reason for the pullback and did not offer a revised timetable for when — or whether — it might try again. The company's Form S-1 registration statement, filed with the U.S. Securities and Exchange Commission under File No. 333-298612, had not yet been declared effective, meaning the offering could be withdrawn without the kind of public unwinding that follows a completed listing. Hank J. Holland, Amaero's chief executive, is named in the release as the company's leader through the episode, though the announcement itself is brief and procedural rather than explanatory beyond the market-conditions line.
A Fast Reversal
The speed of the reversal is what makes this notable. According to reporting from VoxelMatters, published September 23, Amaero had filed for an offering of roughly 7.46 million shares at an assumed price of $7.06 apiece — a deal that would have raised approximately $52.6 million gross before underwriting fees and expenses. That is not a particularly large IPO by Nasdaq standards, but it would have been a meaningful capital event for a company operating in the comparatively narrow niche of spherical metal powder production for 3D printing.
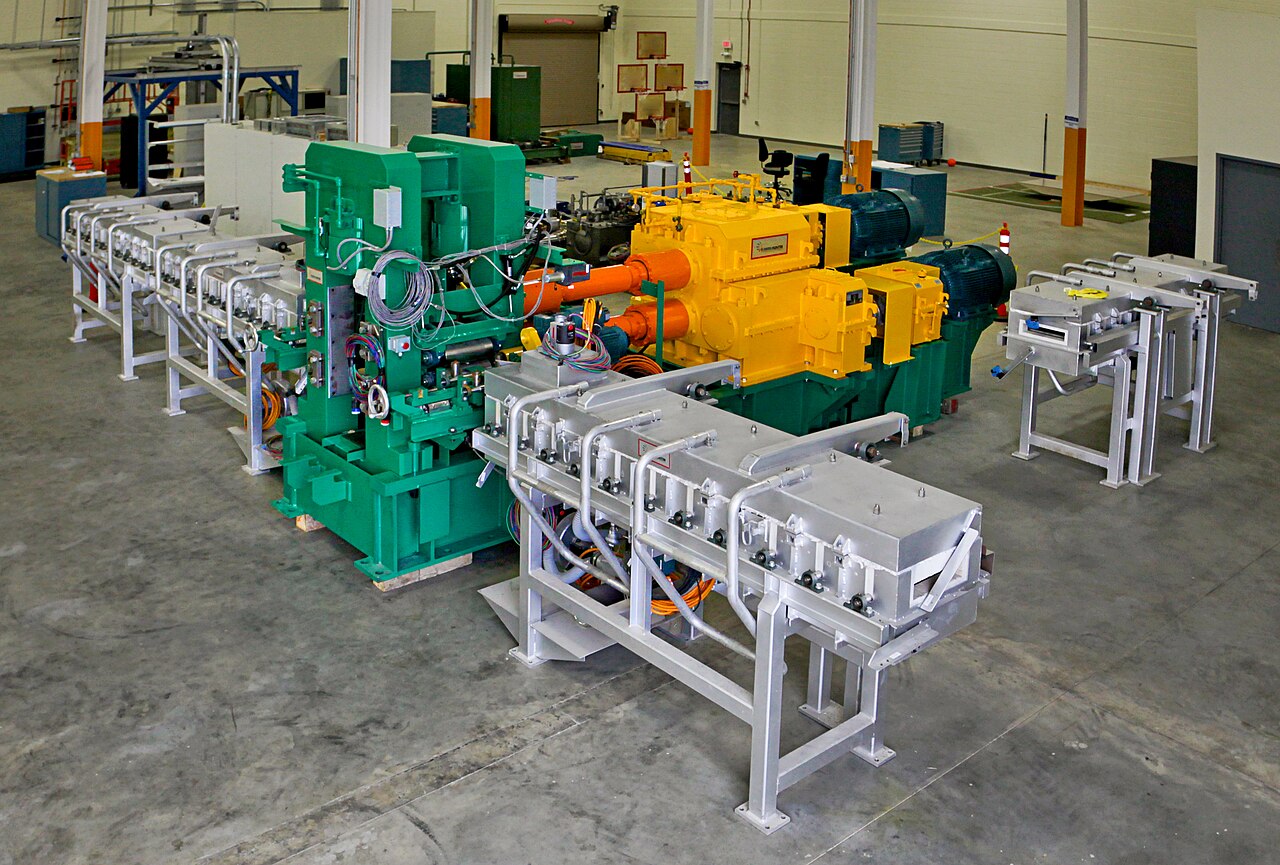
Amaero already trades on the Australian Securities Exchange under the ticker 3DA, and the now-shelved Nasdaq listing would have added a second, larger public market to its capital-raising toolkit. Dual listings of this kind are common for companies trying to tap deeper U.S. institutional capital pools while retaining their home-market trading history and shareholder base. The company's core business is producing titanium and refractory-alloy powders — the feedstock that laser powder bed fusion, electron beam melting, and other metal additive systems consume — at an AS9100D-certified facility in McDonald, Tennessee, where the company runs three Electrode Induction Melting Inert Gas Atomization (EIGA) systems, with a fourth unit scheduled to come online in June 2027, according to VoxelMatters' reporting.
Neither the GlobeNewswire release nor the VoxelMatters report specifies exactly which market signals drove the decision. "Adverse market conditions" is a standard, deliberately vague formulation companies use when withdrawing or postponing offerings — it can refer to broader equity market volatility, weak demand from institutional investors during the roadshow process, unfavorable pricing feedback, or some combination of the three. Because the S-1 had not gone effective, Amaero was not required to disclose granular details of investor demand the way it would have had to once shares began trading.
What It Means for Makers
For the additive manufacturing industry broadly, and metal AM specifically, an IPO postponement by a mid-tier powder supplier is a data point worth watching rather than a crisis. Amaero is not a household name among desktop or prosumer makers — its powders feed industrial metal printing operations, not FDM or resin printers on a hobbyist's bench. Still, the health of feedstock suppliers matters to the entire additive ecosystem, because metal powder production is capital-intensive, consolidation-prone, and sensitive to swings in the same capital markets that fund the printer manufacturers themselves.
A postponed IPO is not a failed company. Plenty of firms pull offerings and return to market weeks or months later once conditions firm up, or they raise privately instead and skip the public listing altogether. But it is also a signal that public-market investors were not lining up to fund metal-powder capacity expansion at the valuation Amaero and its underwriters had assumed. That $7.06 per-share price point implied a specific view of Amaero's growth trajectory and the broader metal AM market's near-term demand curve, and the company's own read of the room — after filing — was that the number wasn't going to hold up well enough to justify pushing forward.
Makers and shops that specify Amaero powders, or that buy from downstream distributors sourcing Amaero material, likely see no immediate operational change. The company continues operating as a publicly traded entity on the ASX regardless of what happens with the Nasdaq plan, and a postponed offering does not by itself affect existing supply agreements or production capacity. The more relevant question for the industry is what a stalled IPO signals about investor appetite for metal AM feedstock plays generally, at a moment when several powder producers and printer OEMs have leaned on public and private capital raises to fund expansion. If institutional investors are cooling on new metal-powder listings, that could make it harder for smaller or newer entrants in the space to raise growth capital on favorable terms, even as demand for metal AM parts in aerospace and defense supply chains remains strong.
What Comes Next
Amaero's release gives no indication of when it might revisit the Nasdaq listing. The S-1 filing itself does not automatically expire, so the company retains the option to update and refile at a later date if market sentiment improves, or it could withdraw the registration statement entirely and pursue alternative financing. Until Amaero says more, the story is simply that a filed offering came off the table within days of being set in motion — a reminder that even a modest, well-telegraphed IPO can be at the mercy of market timing that shifts faster than a roadshow schedule can absorb.
Sources
- Amaero Inc. Postpones U.S. Initial Public Offering — GlobeNewswire, September 24, 2026
- Amaero files for $52.6 million IPO and Nasdaq listing — VoxelMatters, September 23, 2026